First-Time Home Buyer Benefits in Ontario (2026): Every Rebate, Credit and Program You Can Stack
A first-time buyer in Ontario can put up to $100,000 toward a down payment through the FHSA ($40,000) and RRSP Home Buyers' Plan ($60,000), double that as a couple. At closing they can claim a $1,500 federal tax credit, up to $4,000 off Ontario land transfer tax and, in Toronto, up to $4,475 more. On a new build, the federal GST rebate (up to $50,000) and Ontario HST rebate (up to $80,000) can remove the full 13% HST, up to $130,000.
Download the full guide as a PDF
Buying your first home in Ontario comes with more help than most people realize. The trick is that the programs come from different places (the federal government, the province and the City of Toronto) and they kick in at different stages. Here is every one, in the order you use them.
At a glance: first-time buyer benefits in Ontario for 2026
| Benefit | Up to | Who gives it | When you use it |
|---|---|---|---|
| First Home Savings Account (FHSA) | $40,000 | Federal | Saving for your down payment |
| RRSP Home Buyers' Plan | $60,000 | Federal | Saving for your down payment |
| First-Time Home Buyers' Tax Credit | $1,500 | Federal | Your tax return for the year you buy |
| Ontario land transfer tax rebate | $4,000 | Ontario | At closing |
| Toronto land transfer tax rebate | $4,475 | City of Toronto | At closing, Toronto homes only |
| First-time buyers' GST rebate | $50,000 | Federal | New builds only |
| Ontario HST rebate on new homes | $80,000 | Ontario | New builds only |
| 30-year amortization | 30 years | Federal mortgage rules | When you get your mortgage |
Stage 1: Build your down payment
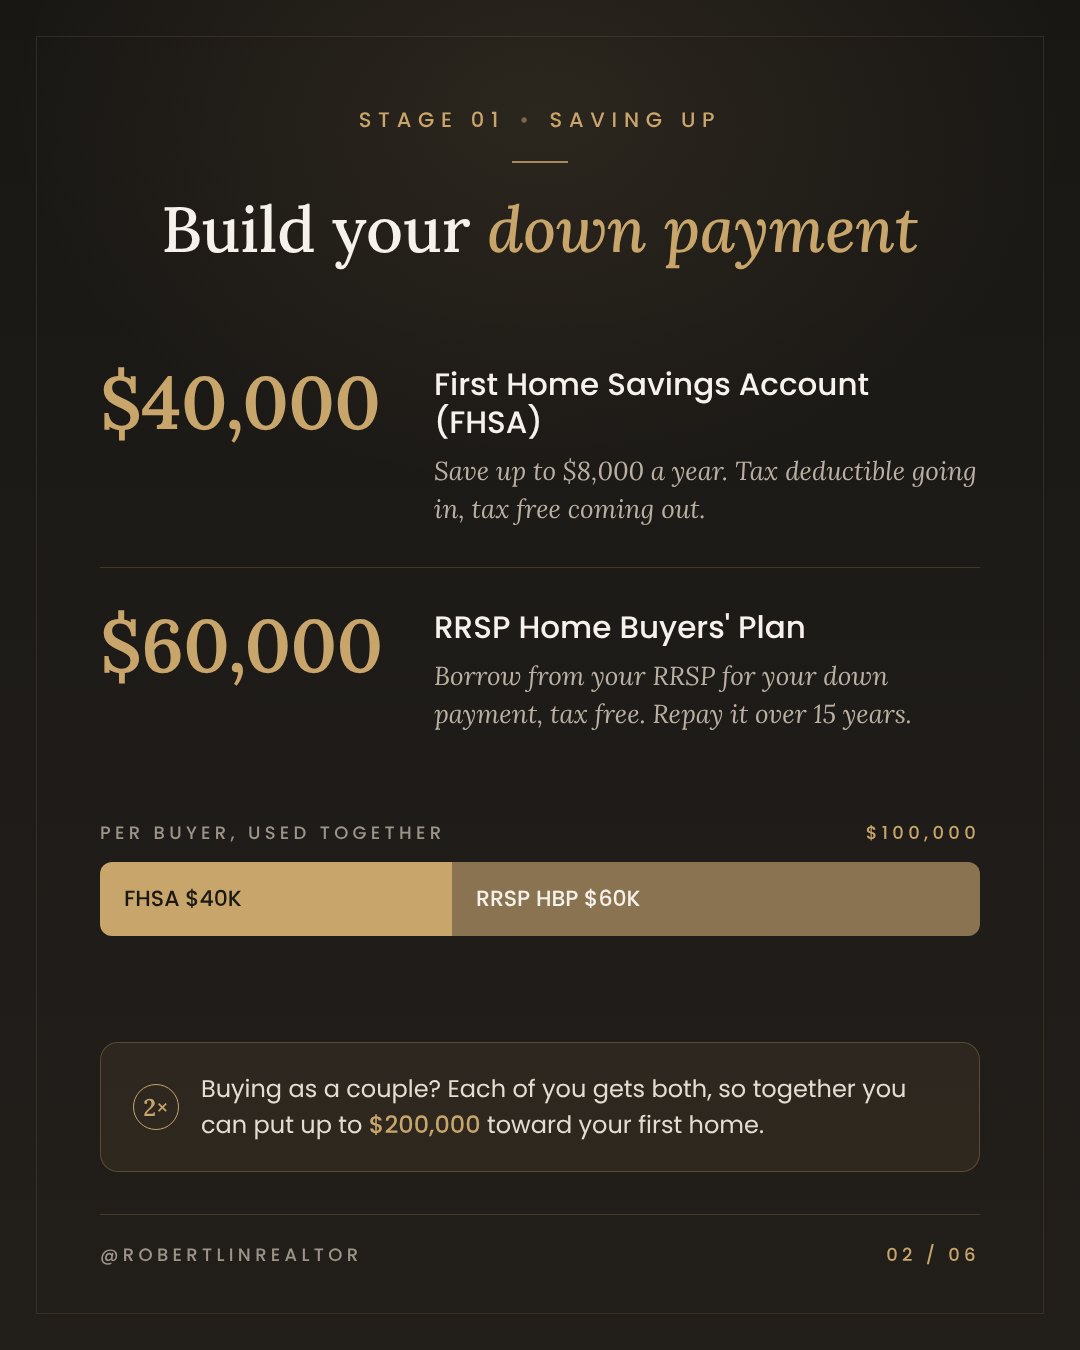
First Home Savings Account (FHSA), up to $40,000
You can put in up to $8,000 a year, to a lifetime total of $40,000. Contributions are tax deductible like an RRSP, and withdrawals for your first home are tax free like a TFSA. Unused room of up to $8,000 carries forward to the next year, so opening an account early is worth it even if you cannot fund it right away.
RRSP Home Buyers' Plan, up to $60,000
You can withdraw up to $60,000 from your RRSP, tax free, for your first home. You pay it back into your RRSP over 15 years.
Use both together. The FHSA and the Home Buyers' Plan can be combined, so one buyer can put up to $100,000 toward a down payment. A couple buying together can each use both, for up to $200,000.
Stage 2: Credits and rebates at tax time and closing
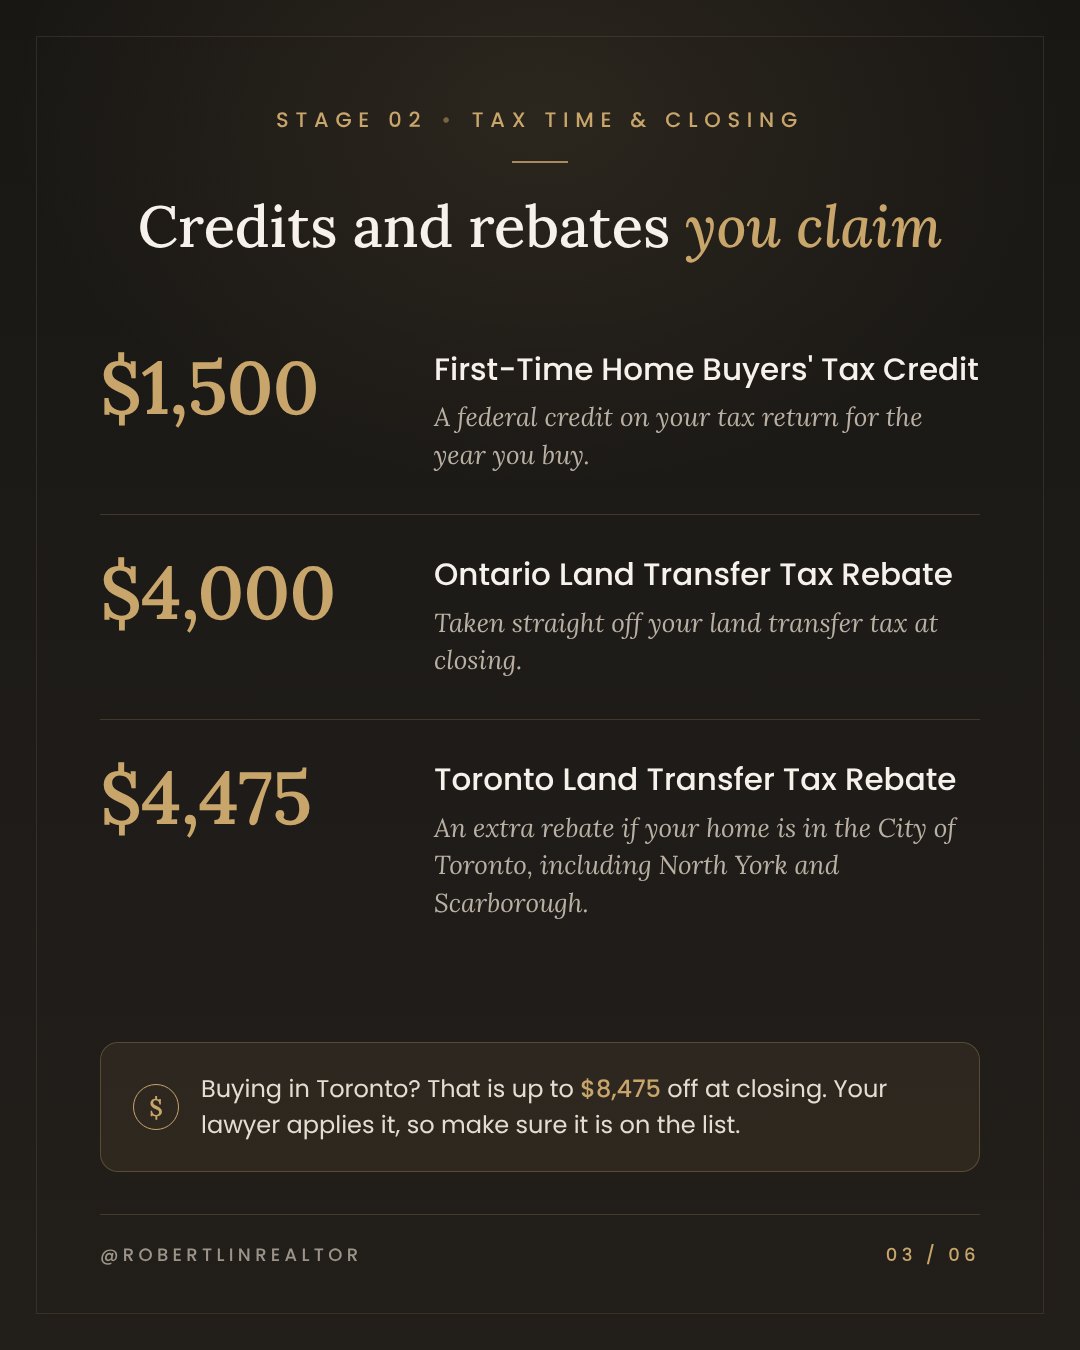
First-Time Home Buyers' Tax Credit, $1,500
You claim $10,000 on your federal tax return for the year you buy, which is worth $1,500 back. A couple can split it, but the total stays at $1,500.
Ontario land transfer tax rebate, up to $4,000
Ontario charges land transfer tax on every purchase. First-time buyers get up to $4,000 off, which covers the full tax on a home up to $368,000. Your lawyer applies it at closing.
Toronto land transfer tax rebate, up to $4,475
If you buy in the City of Toronto, including North York and Scarborough, you also pay Toronto's municipal land transfer tax. First-time buyers get up to $4,475 off that too, so a Toronto first-time buyer can save up to $8,475 at closing. Markham, Vaughan, Richmond Hill and Thornhill do not charge the municipal tax. See my full breakdown in Closing costs in Ontario.
Stage 3: The big one, buying a new build
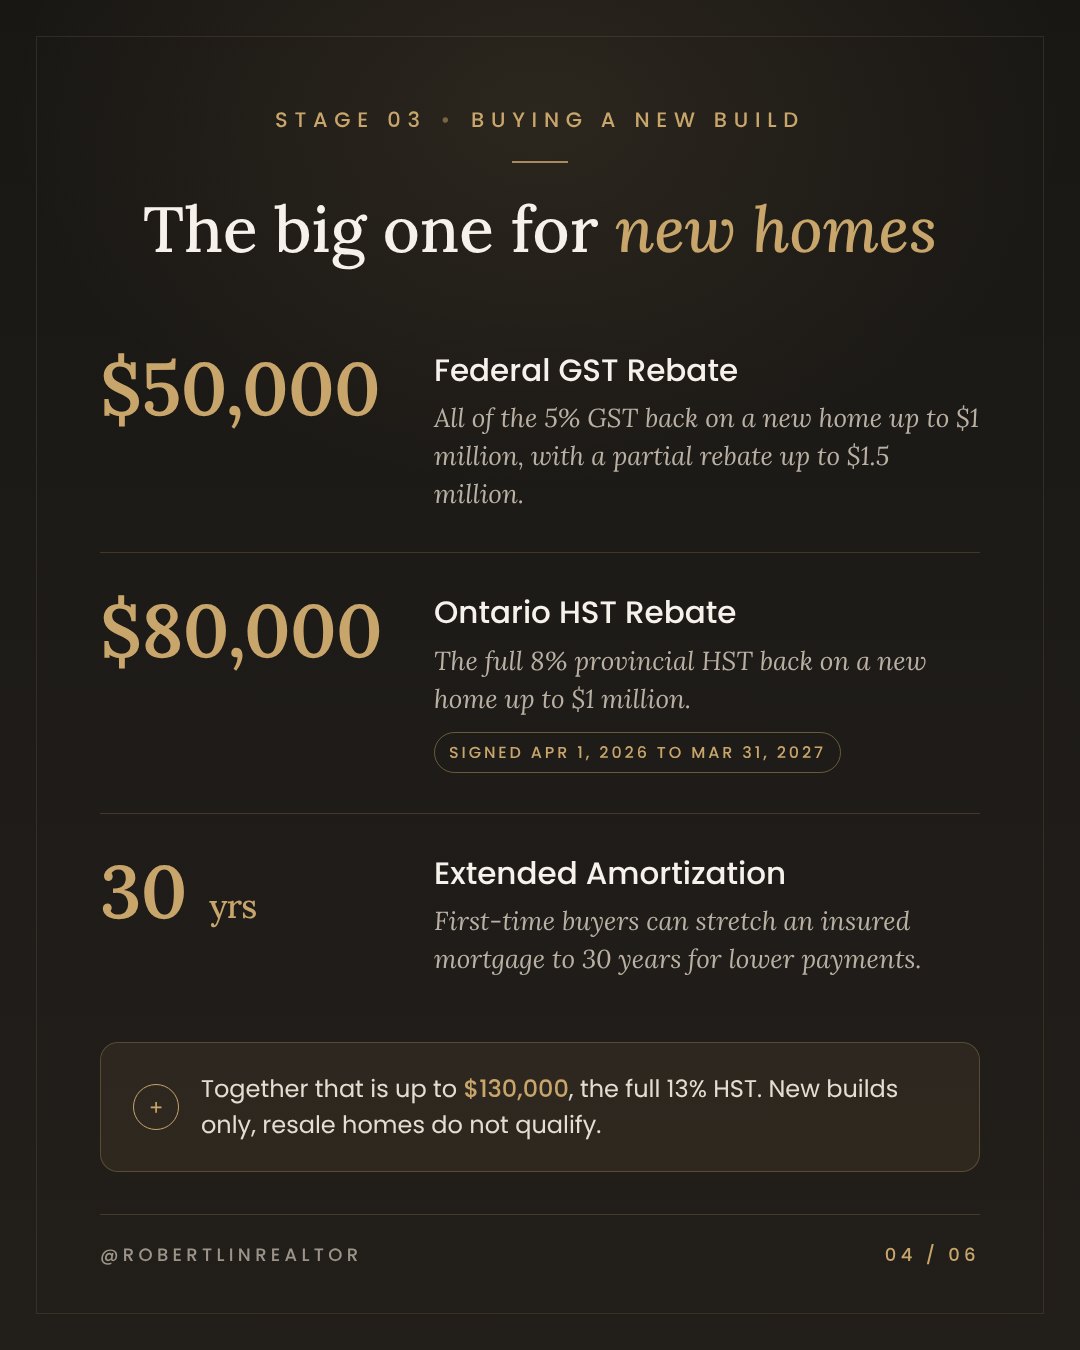
First-time home buyers' GST rebate, up to $50,000
First-time buyers of a newly built home get back all of the 5% GST (the federal part of the HST) on homes up to $1 million, up to $50,000. Between $1 million and $1.5 million the rebate is reduced, and it ends at $1.5 million. It applies to agreements signed from May 27, 2025 onward.
Ontario HST rebate on new homes, up to $80,000
Ontario has enhanced its rebate on the 8% provincial part of the HST: the full 8% back on a new home up to $1 million, to a maximum of $80,000. It covers purchase agreements signed from April 1, 2026 to March 31, 2027, and the home must be your main residence. Confirm the current rules with your lawyer before you sign, as provincial programs can change.
Together that is up to $130,000, the full 13% HST on a new home. Resale homes do not qualify for either new build rebate.
30-year amortization
First-time buyers can take an insured mortgage (less than 20% down) over 30 years instead of 25, which lowers the monthly payment.
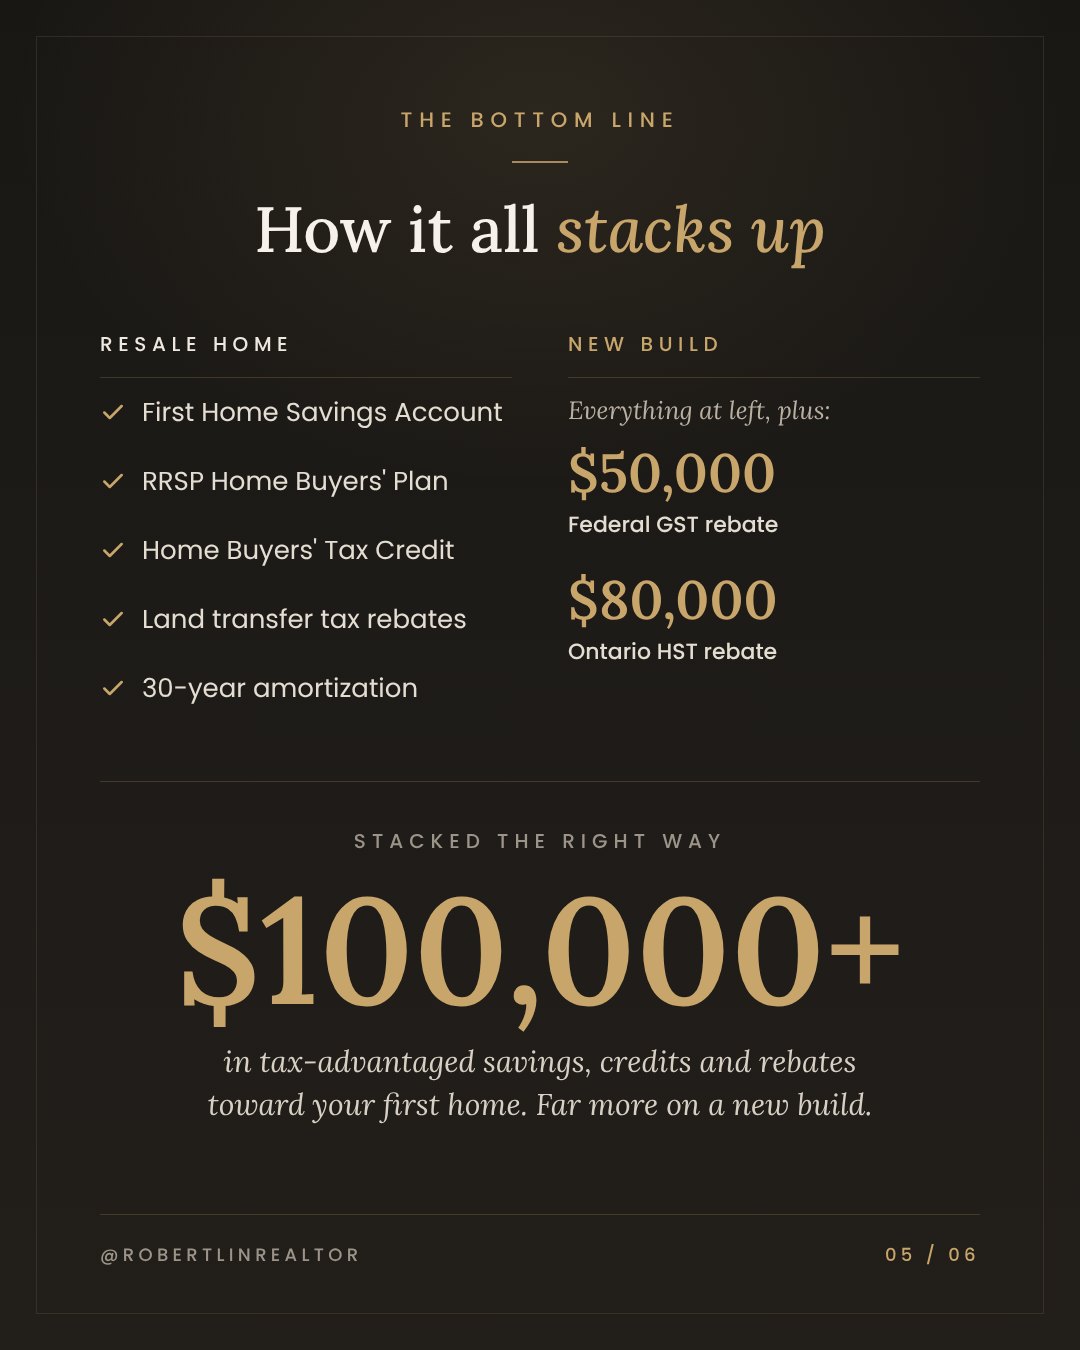
How it all stacks up
On a resale home, a first-time buyer can use the FHSA, the Home Buyers' Plan, the $1,500 tax credit, the land transfer tax rebates and a 30-year amortization. On a new build, add the federal GST rebate and the Ontario HST rebate on top. Stacked the right way, that is over $100,000 in tax-advantaged savings, credits and rebates toward your first home, and far more on a new build.
Common questions from first-time buyers
What counts as a first-time home buyer in Ontario?
For most programs, you are a first-time buyer if you have not owned and lived in a home in the last four years. The Ontario land transfer tax rebate is stricter: you must never have owned a home anywhere in the world, and neither can your spouse while you were together. Rules differ slightly by program, so check each one.
Can I use the FHSA and the RRSP Home Buyers' Plan together?
Yes. You can use both for the same home, for a combined total of up to $100,000 per person.
How much can a first-time buyer save on land transfer tax in Toronto?
Up to $8,475: $4,000 off the Ontario land transfer tax and $4,475 off Toronto's municipal land transfer tax. Outside Toronto, in places like Markham, Vaughan and Richmond Hill, there is no municipal tax, so the rebate is up to $4,000.
Do first-time buyers pay HST on a new home in Ontario?
On a new home up to $1 million, a first-time buyer can get back all of the HST: up to $50,000 through the federal GST rebate and up to $80,000 through Ontario's HST rebate, if the purchase agreement falls within each program's dates.
Does the GST rebate apply to resale homes?
No. The first-time buyers' GST rebate and the Ontario HST rebate only apply to newly built or substantially renovated homes. Resale homes do not have GST or HST on the price.
Want to know which ones you qualify for?
Every buyer's mix is different. I will go through which benefits apply to you and how to stack them, step by step. Send me a message or call or text 647-965-7834. For the full buying process, read Buying your first home, step by step.
General information for Ontario and the GTA, current as of November 2026. Not tax or legal advice. Confirm your eligibility with your lawyer or accountant.
Written by Robert Lin
Real estate agent serving Thornhill, Markham, Vaughan, Richmond Hill, North York, Scarborough, Toronto. Questions about your situation? Send me a message or call 647-965-7834.
More guides
Should You Buy First or Sell First? A Guide for Move Up Families in Markham and York Region
Moving up to a bigger home in Markham, Thornhill, Richmond Hill or Vaughan? How to decide whether to buy first or sell first, how bridge financing works, and how to line up your closing dates.
BuyersTop Ranked High Schools in Markham, Richmond Hill and Thornhill (2025 Fraser Rankings): What Home Buyers Should Know
The top ranked high schools in Markham, Richmond Hill and Thornhill from the 2025 Fraser Institute report, and what home buyers need to check before buying for a school zone.
NeighbourhoodsMarkham Neighbourhood Guide: Communities, Transit and Schools
A local agent's guide to buying a home in Markham, Ontario, covering its main communities from Unionville and Cornell to Berczy and Milliken Mills, plus transit, schools, hospitals and what is changing in Downtown Markham.